Leverage Trading Explained
Leverage trading explained: what the ratio means, how it differs from margin, the FCA and CFTC retail limits, and why the ratio is not your risk.
Leverage lets a deposit control a larger position, and it is written as a ratio between the two: at 100:1, $1,000 of your money holds a $100,000 position. The ratio works the same way in both directions, so it sets how large a position the account can open and how fast a move against you eats the deposit.
How much of it a retail client can use is set by the regulator that authorises the provider, and two of those regulators publish the numbers themselves. The UK's rules are in the FCA Handbook. The floor for US off-exchange retail forex is in the CFTC's own regulations. Both are quoted here, with the limit they state and what each says about how long it holds.
Is leverage the same as margin?
No. Margin is the money held against the position. Leverage is the ratio that follows from it. They move in opposite directions.
Some education pages use the words interchangeably. WealthWithin, last updated 13 March 2026: "Leverage trading, also known as margin trading, is a strategy that allows traders to control larger positions using a smaller amount of initial capital." ActivTrades, August 14, 2025, treats margin as the deposit: traders "put down a small deposit (also known as a margin) but still gain exposure with larger positions".
ATFX, last updated July 17, 2024, separates them and publishes the conversion. Margin, it says, "is the percentage of the full value of the trade that you must deposit to open a leveraged position", while "Leverage is the factor by which you can increase your trade size compared to your margin". Its table, as printed on its page:
| Margin | Leverage ratio |
|---|---|
| 10% | 10:1 |
| 5% | 20:1 |
| 3% | 33:1 |
| 2% | 50:1 |
| 1% | 100:1 |
| 0.5% | 200:1 |
That conversion matters, because the FCA writes its limits as a margin percentage rather than as a ratio.
The same ratio gets written both ways round. ActivTrades writes 500:1 and ATFX writes 100:1. B2Broker writes 1:25 to 1:1000. PrimeXBT, dated January 22, 2025, uses both on one page, "a leverage ratio of 1:100" in its text and 100:1 in its own table. In every case the big number is the position and the small one is the deposit.
How does leverage trading work, with an example?
The deposit is a fraction of the position, and the fraction is the inverse of the ratio.
ATFX gives it in one line: "If you want to open a $100,000 trade position in the forex market with leverage of 100:1, you'd need a margin of 1% or $1,000. With a 50:1 leverage ratio, the required margin would be 2% or $2,000."
A 2% move against a position held at 50:1 wipes out the margin put up for it. Nothing about the ratio changes the size of the price move. It changes how much of your deposit that move represents, and how little room the position has before the provider closes it.
What is the maximum retail leverage?
It is whatever the provider's regulator allows, so there is no single worldwide number.
The UK: the FCA writes a minimum margin, not a ratio
The FCA Handbook, COBS 22.5.11R, says a firm "must require a retail client to post margin to open a position of at least the following amounts", as a percentage of the exposure the trade provides:
| Underlying asset, as the FCA lists it | Minimum margin | Same thing as a ratio |
|---|---|---|
| a major foreign exchange pair or relevant sovereign debt | 3.33% | about 30:1 |
| a major stock market index, minor foreign exchange pair or gold | 5% | 20:1 |
| a minor stock market index or a commodity other than gold | 10% | 10:1 |
| a share or an asset not otherwise listed | 20% | 5:1 |
The Handbook shows 6 January 2021 for that rule, and it sits in the Handbook rather than in a temporary measure, so it is the standing UK position rather than something with an announced expiry. A rule from the same date puts cryptoasset derivatives outside this section entirely and points firms to a separate prohibition: "Firms are reminded of the prohibitions in relation to the marketing, distribution and sale of cryptoasset derivatives in COBS 22.6."
The FCA also fixes the warning a firm has to put in front of retail clients, in COBS 22.5.6R: "CFDs are complex instruments and come with a high risk of losing money rapidly due to leverage. [insert percentage per provider]% of retail investor accounts lose money when trading CFDs with this provider. You should consider whether you understand how CFDs work and whether you can afford to take the high risk of losing your money." The percentage in that sentence is the firm's own, which is why it differs from one provider's website to another's.
The EU: ESMA's 2018 limits were temporary by design
ESMA's announcement of 27 March 2018 set leverage limits "on the opening of a position by a retail client from 30:1 to 2:1, which vary according to the volatility of the underlying":
| Instrument, as ESMA wrote it | Limit |
|---|---|
| major currency pairs | 30:1 |
| non-major currency pairs, gold and major indices | 20:1 |
| commodities other than gold and non-major equity indices | 10:1 |
| individual equities and other reference values | 5:1 |
| cryptocurrencies | 2:1 |
That announcement states its own shelf life. "In accordance with MiFIR, ESMA can only introduce temporary intervention measures on a three monthly basis. Before the end of the three months, ESMA will consider the need to extend the intervention measures for a further three months."
ESMA's standing page on product intervention says what happened next. Its own measures "are temporary and cannot exceed three months", while "In contrast, NCAs' adopted measures can be permanent." The 2018 CFD measure took effect on 1 August 2018 and was renewed in three-month steps until March 2019. Then: "between March 2019 and April 2020 NCAs adopted product intervention measures in their jurisdictions", and "Those product intervention measures by NCAs replaced ESMA's prior temporary measures and ensured the continued protection of retail investors."
So ESMA's 2018 measure is not the rule in force anywhere today. The rule in force in an EU country is that country's own national measure, published by its national regulator, which is where to look for a current number.
The US: the CFTC sets a floor and the NFA sets the number
For off-exchange retail forex, 17 CFR 5.9 requires a dealer to collect a minimum security deposit "equal to the applicable percentage as set by the registered futures association of which they are a member", with a floor: "the registered futures association's security deposit requirement cannot be less than: (1) 2% of the notional value of the retail forex transaction for major currency pairs and 5% of the notional value of the retail forex transaction for all other currency pairs".
Two per cent is 50:1 and five per cent is 20:1, and those are floors rather than the figures in force. The registered futures association, the NFA, sets the actual percentage, and the regulation requires it to "designate which currencies are "major currencies", and shall review, no less frequently than annually, major currency designations and security deposit requirements, and shall adjust the designations and requirements as necessary." The number in force is therefore the NFA's own published requirement, and it can change every year, so read it there rather than taking the floor as the limit.
Two practical cautions
A number from a broker's education page is not a regulator's number. ActivTrades puts an asterisk under its own list: "These numbers can be significantly higher if trading with offshore brokers or certain platforms." And OANDA names no maximum of its own: "Regulators across the globe set maximum leverage limits to help retail traders avoid excess risk. At OANDA, we publish current leverage rates on our website."
Which of these regimes covers an account depends on where the provider is authorised and how it classifies the client. That pairing, provider and client category, is in the account agreement and on the provider's own rates page.
What happens when leverage goes against you?
Three things can happen, in this order, and which of them applies depends on the provider and the jurisdiction.
A margin call comes first. B2Broker describes it as a request from the broker to top the account up "because the margin on his account is close to zero", and says that if that does not happen "the transaction will be closed when the trading account balance reaches 0".
Then a forced close out, and in the UK the trigger is a rule rather than a house policy. FCA COBS 22.5.13R: a firm "must ensure a retail client's net equity in an account used to trade restricted speculative investments does not fall below 50% of the margin requirement", and where it does, the firm "must close the retail client's open position(s) on restricted speculative investments as soon as market conditions allow." Net equity, the same rule says, is "the sum of the retail client's net profit and loss on their open position(s) and the retail client's deposited margin". ESMA's 2018 measure set the same 50% level for the EU, standardising "the percentage of margin (at 50% of minimum required margin) at which providers are required to close out one or more retail client's open CFDs".
Last, negative balance protection, which exists where a rule creates it. FCA COBS 22.5.17R: "The liability of a retail client for all restricted speculative investments connected to the retail client's account is limited to the funds in that account", and its guidance adds that this "means that a retail client cannot lose more than the funds specifically dedicated to trading restricted speculative investments." ESMA's 2018 measure included the same protection per account. Where no such rule applies, the outcome can be the one ActivTrades describes when writing about high leverage and flash crashes: losses may exceed the deposit and "you may end up being in debt to the broker". That is a feature of the account's rulebook, not of leverage itself.
Does leverage change my risk per trade?
No. The loss on a trade is set by your position size and your stop, and the leverage ratio is not in that calculation.
Our own position size calculator publishes the formula:
position size = money at risk / (stop distance x value of 1 pip or point per lot)
There is no leverage term in it. Money at risk is your balance times your risk percent, the stop distance is yours, and the pip or point value belongs to the instrument. Leverage decides how much of the account is tied up as margin and how large a position the account is allowed to open. Those are two different numbers, and plenty of explainers treat them as one.
PrimeXBT is one of the few that names the other number: "It is crucial to understand how much you are willing to risk per trade, from both a statistical standpoint and an emotional comfort standpoint." WealthWithin tells readers to use stop losses, adjust position sizes and practise on a demo account.
What ratio to use is set by your provider inside its regulator's limits. Nothing here is advice to trade at any size.
Lot size, contract size and leverage
Leverage does not change the size of a lot. It changes the deposit required to hold one.
A lot is a fixed quantity of the instrument. Our calculator states the unit it uses: "A standard lot is 100,000 units of the base currency." Contract sizes for other instruments are not standard across the market, and the same page's FAQ says so: gold, silver and index contract sizes vary by broker, which is why the calculator asks you for the value rather than assuming one. Work out the size from your risk and your stop in the position size calculator, then check what margin your provider holds against that size.
Do prop firms use leverage?
Yes, and each firm sets its own cap inside its own rules, which differ by firm and by challenge type. Those caps belong on each firm's own page.
What we publish is how backtested trades score against those rule sets: see prop firm backtesting. ChartLabs scores your trades against challenge rules. It does not provide funding and is not a challenge.
Can I practise this before risking money?
You can practise the part that is in your control: the size and the stop.
In ChartLabs you trade historical charts bar by bar, and, in our calculator's own words, "the order bar sizes each position from your risk percent and stop distance. Every trade then feeds your stats." The control sits on the order bar next to the order type:
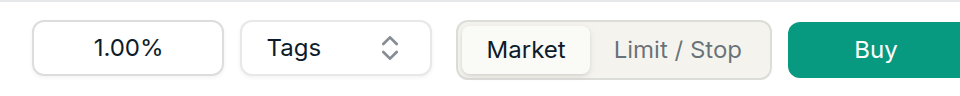
That is one percent of the account balance put at risk on the trade, translated into a position size by the stop you placed. Change the stop and the size changes; the risk stays where you set it. Over a sample of trades it is that discipline, rather than the ratio your provider allows, that decides how long the account survives a losing run. The drawdown calculator shows what a given risk percent does to a balance across a streak.
A historical replay is not your broker's account: your provider's margin, close out and protection rules are in your account agreement, and they are what will apply to real money. And no amount of testing makes an outcome certain.
If you want to practise sizing and stops on real historical data before any of this costs money, start a free trial. Seven days, the full platform, no card needed.
Tags
Related Articles
Prop Firm Backtesting: See Which Challenges Your Strategy Would Pass
ChartLabs re-scores your backtested trades against real prop firm challenge rules, so you can see which challenges your strategy would pass and what sizing would change that. It is a scorer, not a funded account: ChartLabs does not connect to a prop firm, place live trades, or provide funding.
Backtesting Accuracy: How Slippage and Data Quality Matter
Why backtest results and live results drift apart, and what actually closes the gap: clean tick data, honest spread assumptions, and commission and slippage modelled directly on every trade you log.